ServicesPersonal Funding
Personal Funding in Plant City
Denied for a loan or credit line and not sure why? We pull your credit reports, find the real reason, and fix that first. Then we plan your applications so each one has a fair shot instead of piling up inquiries.
What personal funding help means here
Personal funding is help getting approved for things like personal loans, credit cards and personal credit lines. We do not lend money. We get your credit file ready and help you decide where and when to apply.
Most people who call us have already tried and been turned down. The denial letter usually gives a vague reason, like too many inquiries or a high balance. That is a starting point, not an answer. We go through all three credit reports line by line to see what a lender actually sees.
Sometimes the fix is small, like paying one card below a certain balance before the statement closes. Sometimes it is an error that needs a dispute, and that work runs through our credit repair service. Either way, you know the cause before you apply again.
What the work includes
- 01
Three-bureau report review
We read your Equifax, Experian and TransUnion reports side by side. Lenders do not all pull the same one, and a problem on one report can sink an application that looks fine on another.
- 02
A clear reason for past denials
We match what is on your reports to the denial reasons you received. You get a plain answer about what caused it.
- 03
Utilization and balance timing
High card balances drag a score down fast. We show you which balances matter most and when they get reported, so you can pay at the right time.
- 04
Inquiry check
We count recent hard inquiries and note when they will stop weighing on your score. That tells us how long to wait before the next application.
- 05
An application plan
We help you choose what to apply for and in what order. The goal is fewer applications with better odds, not a shotgun approach.
- 06
Referral to credit repair when needed
If we find wrong late payments, duplicate accounts or old debts that should not be there, we explain how disputes would work through our credit repair program before you decide.
Questions about Personal Funding?
Call(813) 452-4950Signs it is time to get help
You keep getting denied
Two or more denials in a short stretch means something specific is wrong. Applying again without fixing it just adds another inquiry.
Approved, but for very little
A tiny limit or a high rate often points to one or two items on your report. Those can usually be found and addressed.
Your score dropped and you do not know why
A sudden drop can come from a reported balance, a collection you never heard about or an account that is not yours. We find which one.
You have a big purchase coming
If you plan to finance a car, consolidate debt or open a credit line in the next several months, now is the time to look at your file.
Your reports do not match
Different addresses, accounts or balances across the three bureaus can confuse lenders and slow approvals.
How it works, step by step
- 1
A phone call first
You tell us what you want to qualify for and what has happened so far. We ask about past denials and any letters you got.
- 2
We pull and read your reports
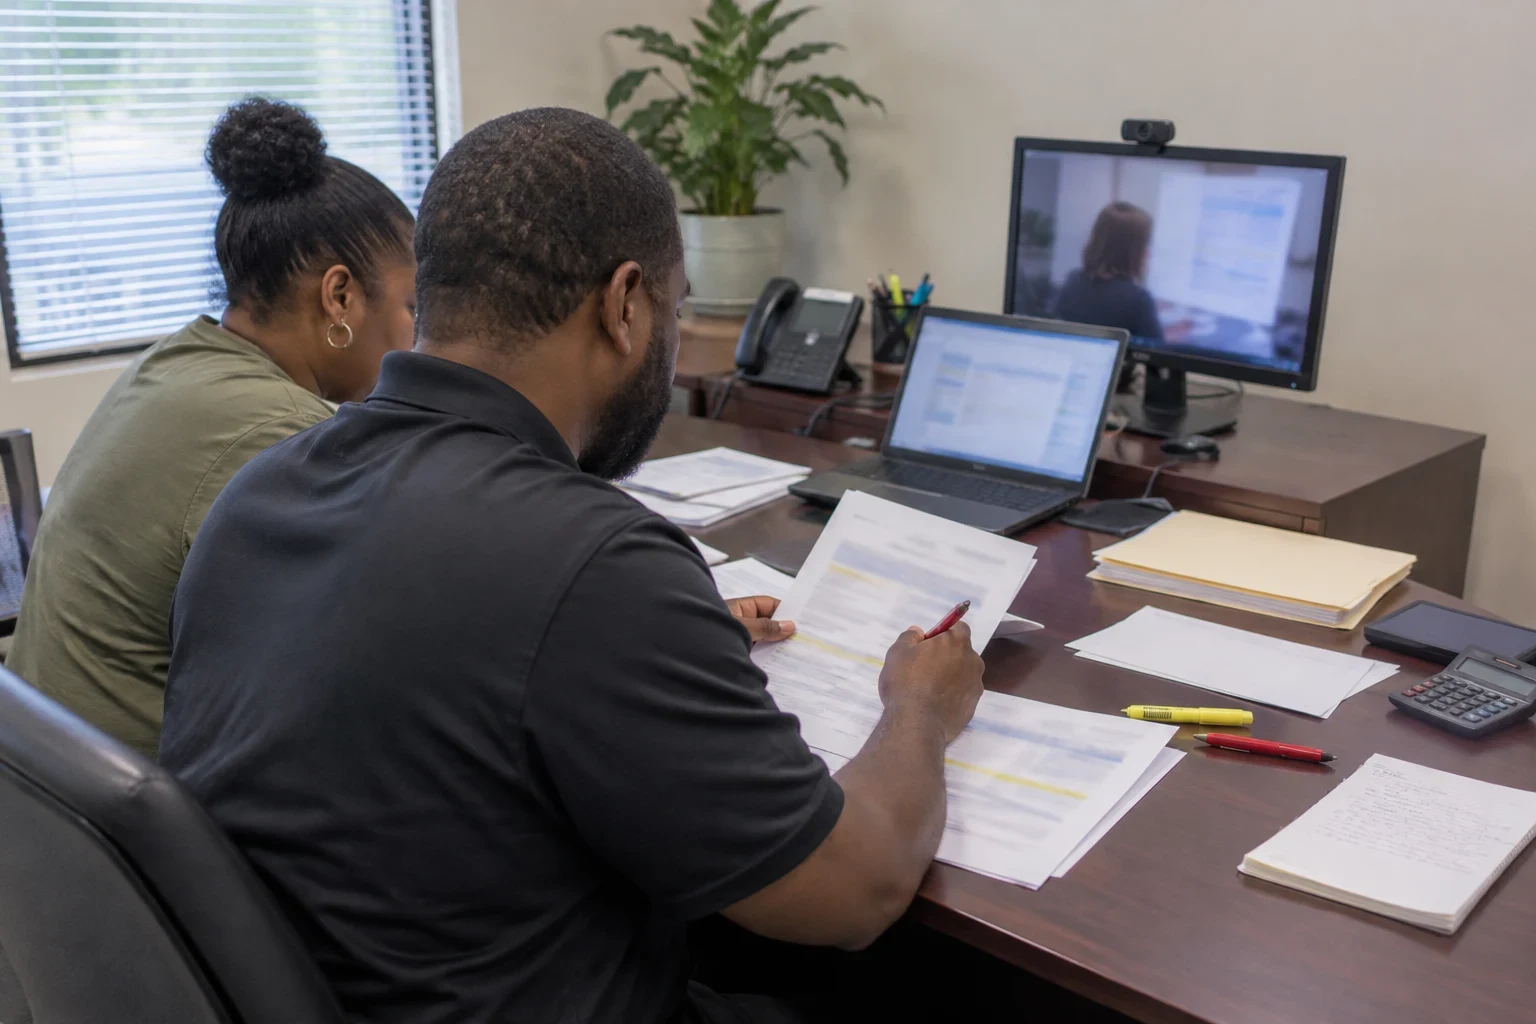
We go through all three credit reports with you at our office or over a video call. Nothing gets skipped.
- 3
We name the cause
You get a short list of what is holding you back, ranked by how much it matters. Some items you can handle yourself. Some need disputes.
- 4
We fix what needs fixing
You pay down the right balances on the right dates, and any disputes go through credit repair. We check your reports again as things update.
- 5
You apply with a plan
Once the file is ready, we go over which products to apply for and in what order. Then you apply knowing what the lender will see.
What moves the cost
Your price depends on what your credit file needs. If your reports are clean and you mostly need a plan, the work is light. If there are errors on all three reports, it takes a lot more. We go over the cost with you on the phone before you sign up for anything.
- How much is on your reports
- A couple of late payments is a smaller job than several collections, a charge-off and accounts that do not belong to you.
- Whether disputes are needed
- When errors have to be disputed with the bureaus or the creditors, that work goes through a credit repair program and widens the scope.
- How many goals you have
- Getting ready for one personal loan is simpler than planning a car loan, a credit line and a new card over the coming year.
- How long you need us
- Some clients need one review and a plan. Others want us keeping an eye on their reports month to month until they are ready to apply.
Personal funding questions
Can you guarantee I get approved?
No. Lenders make the final call, and anyone promising approval is not being straight with you. What we can do is find what is hurting your file, help fix it and help you apply where your odds are better.
Will checking my credit with you lower my score?
Pulling your own reports for review is a soft inquiry and does not hurt your score. Hard inquiries happen when you apply with a lender, which is why we plan those applications carefully.
How long before I can apply again?
It depends on what we find. If it is mostly high balances, it can be a statement cycle or two. If errors need disputes, it takes longer, and we will tell you a realistic timeline after the review.
Do I need credit repair before funding?
Not always. Plenty of clients just need a clear read on their file and better timing. If your reports have errors that are costing you approvals, we will explain what the credit repair process would involve so you can decide.
Do I have to come to the office?
No. You can meet us at our office or do the whole thing by phone and video. Clients from Brandon, Lakeland and Valrico often handle it all by video.
What should I have ready for the call?
Any denial letters you received, a rough list of your cards and loans, and an idea of what you want to qualify for. If you do not have those handy, we can still start.
Find out what is really blocking your approval
One call and we can tell you how we would look at your file and what the next steps are. If credit repair makes sense first, we will say so.